You own the land. Most Acton homeowners fund the build with a home equity loan, a HELOC, a cash-out refinance, or a construction loan. We work with multiple lending partners to find the right fit for you, with flexible credit requirements that meet your needs.
Most families do not write a check for the whole project. They borrow against the home they already own, and the ADU adds value that supports the loan. Here is the plain-language version of each option; the lender will walk you through the fine print.
Borrow against the equity in your home. A home equity loan gives you a lump sum at a fixed rate; a HELOC is a line you draw on as the build progresses. Your first mortgage stays untouched.
Best for homeowners with meaningful equity and a low existing mortgage rate they want to keep.
Replace your current mortgage with a larger one and take the difference in cash to fund the ADU. Simple to manage, and the new payment can be offset by rental income.
Makes sense when current rates are close to your existing rate, or when you want to consolidate.
A loan sized to the finished value of your property with the ADU, released in draws as construction milestones are met.
Best when existing equity is limited but the finished project will appraise well.
Many families fund part of the build from savings or a family contribution and borrow the rest. A smaller loan means faster approval and a lighter monthly payment.
Common for Family Integrity Planning projects where a parent or adult child is contributing.
Loan programs, rates, and terms are set by the lender and depend on your property, income, and credit. Acton ADU makes the introduction and supports the lender's process; the lender handles qualification and approval.
Homeowners often start by asking what the ADU will rent for. Our savviest clients look at the whole picture, and rent is the smallest piece of it.
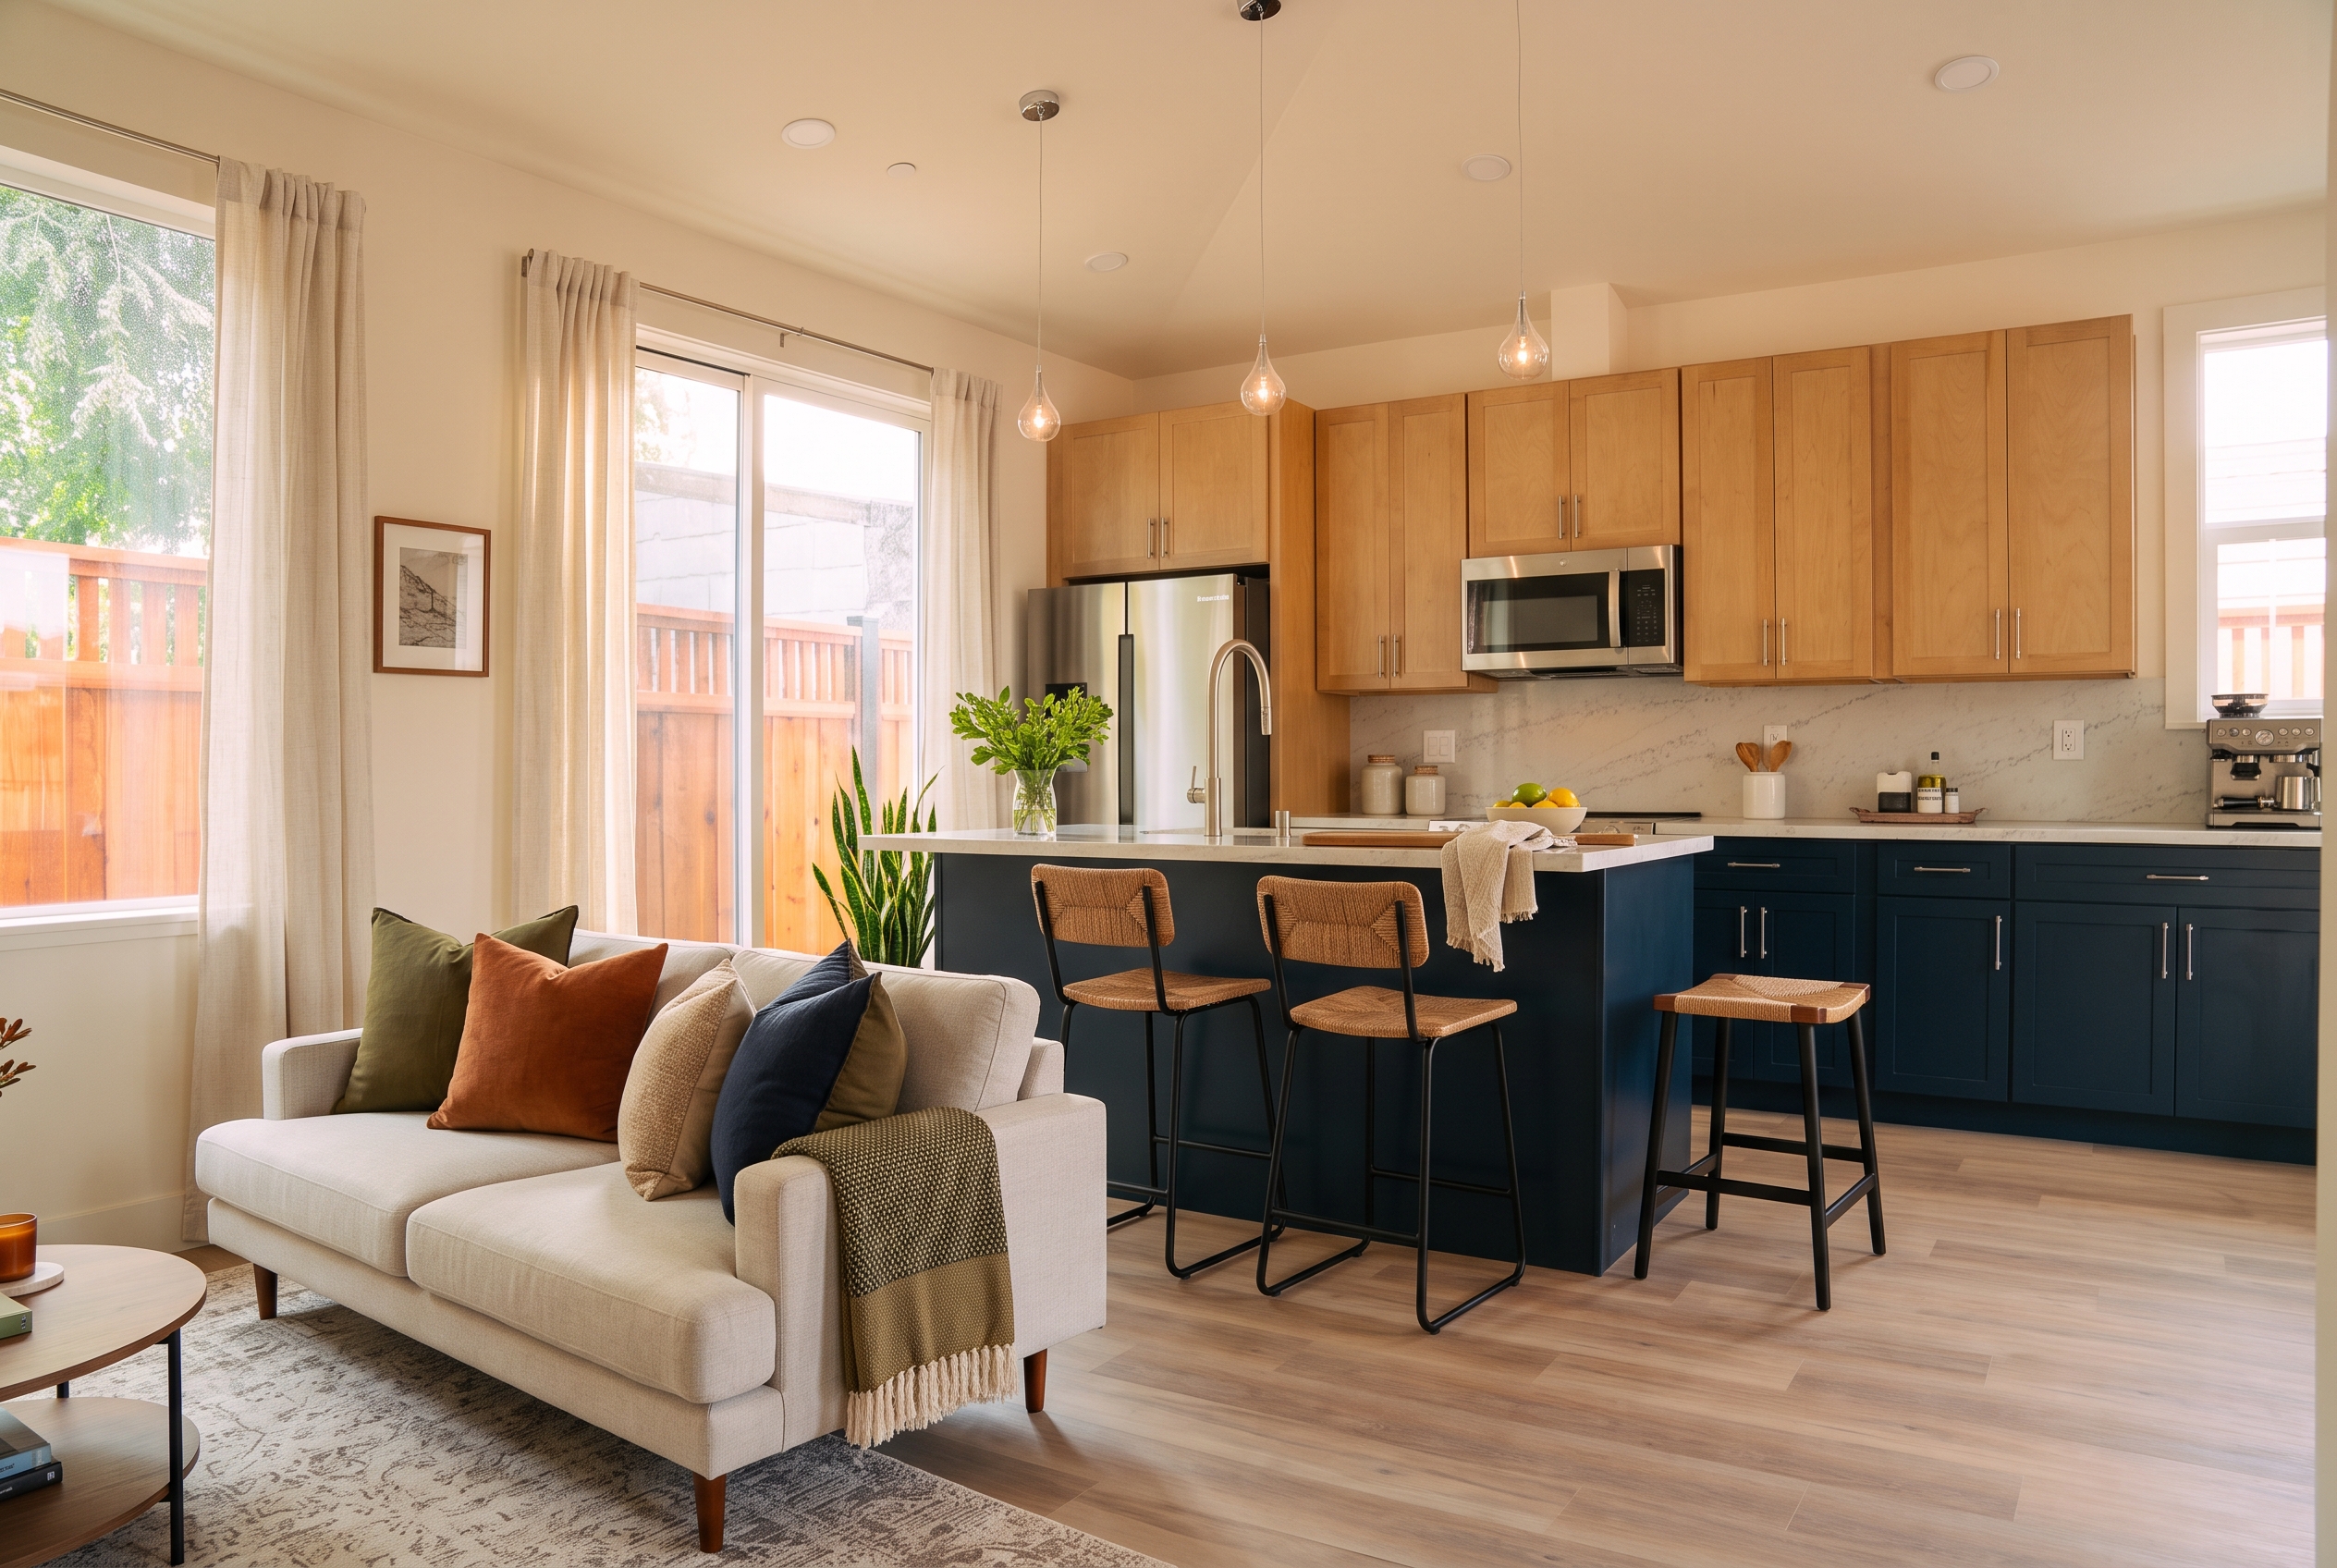
It is no different than two homes of the same size on the same street selling for very different prices. Design, quality, and craftsmanship are the difference, and they are what an appraiser and a renter both pay for. That is why quality is an investment, not a cost, when the goal is long-term value.
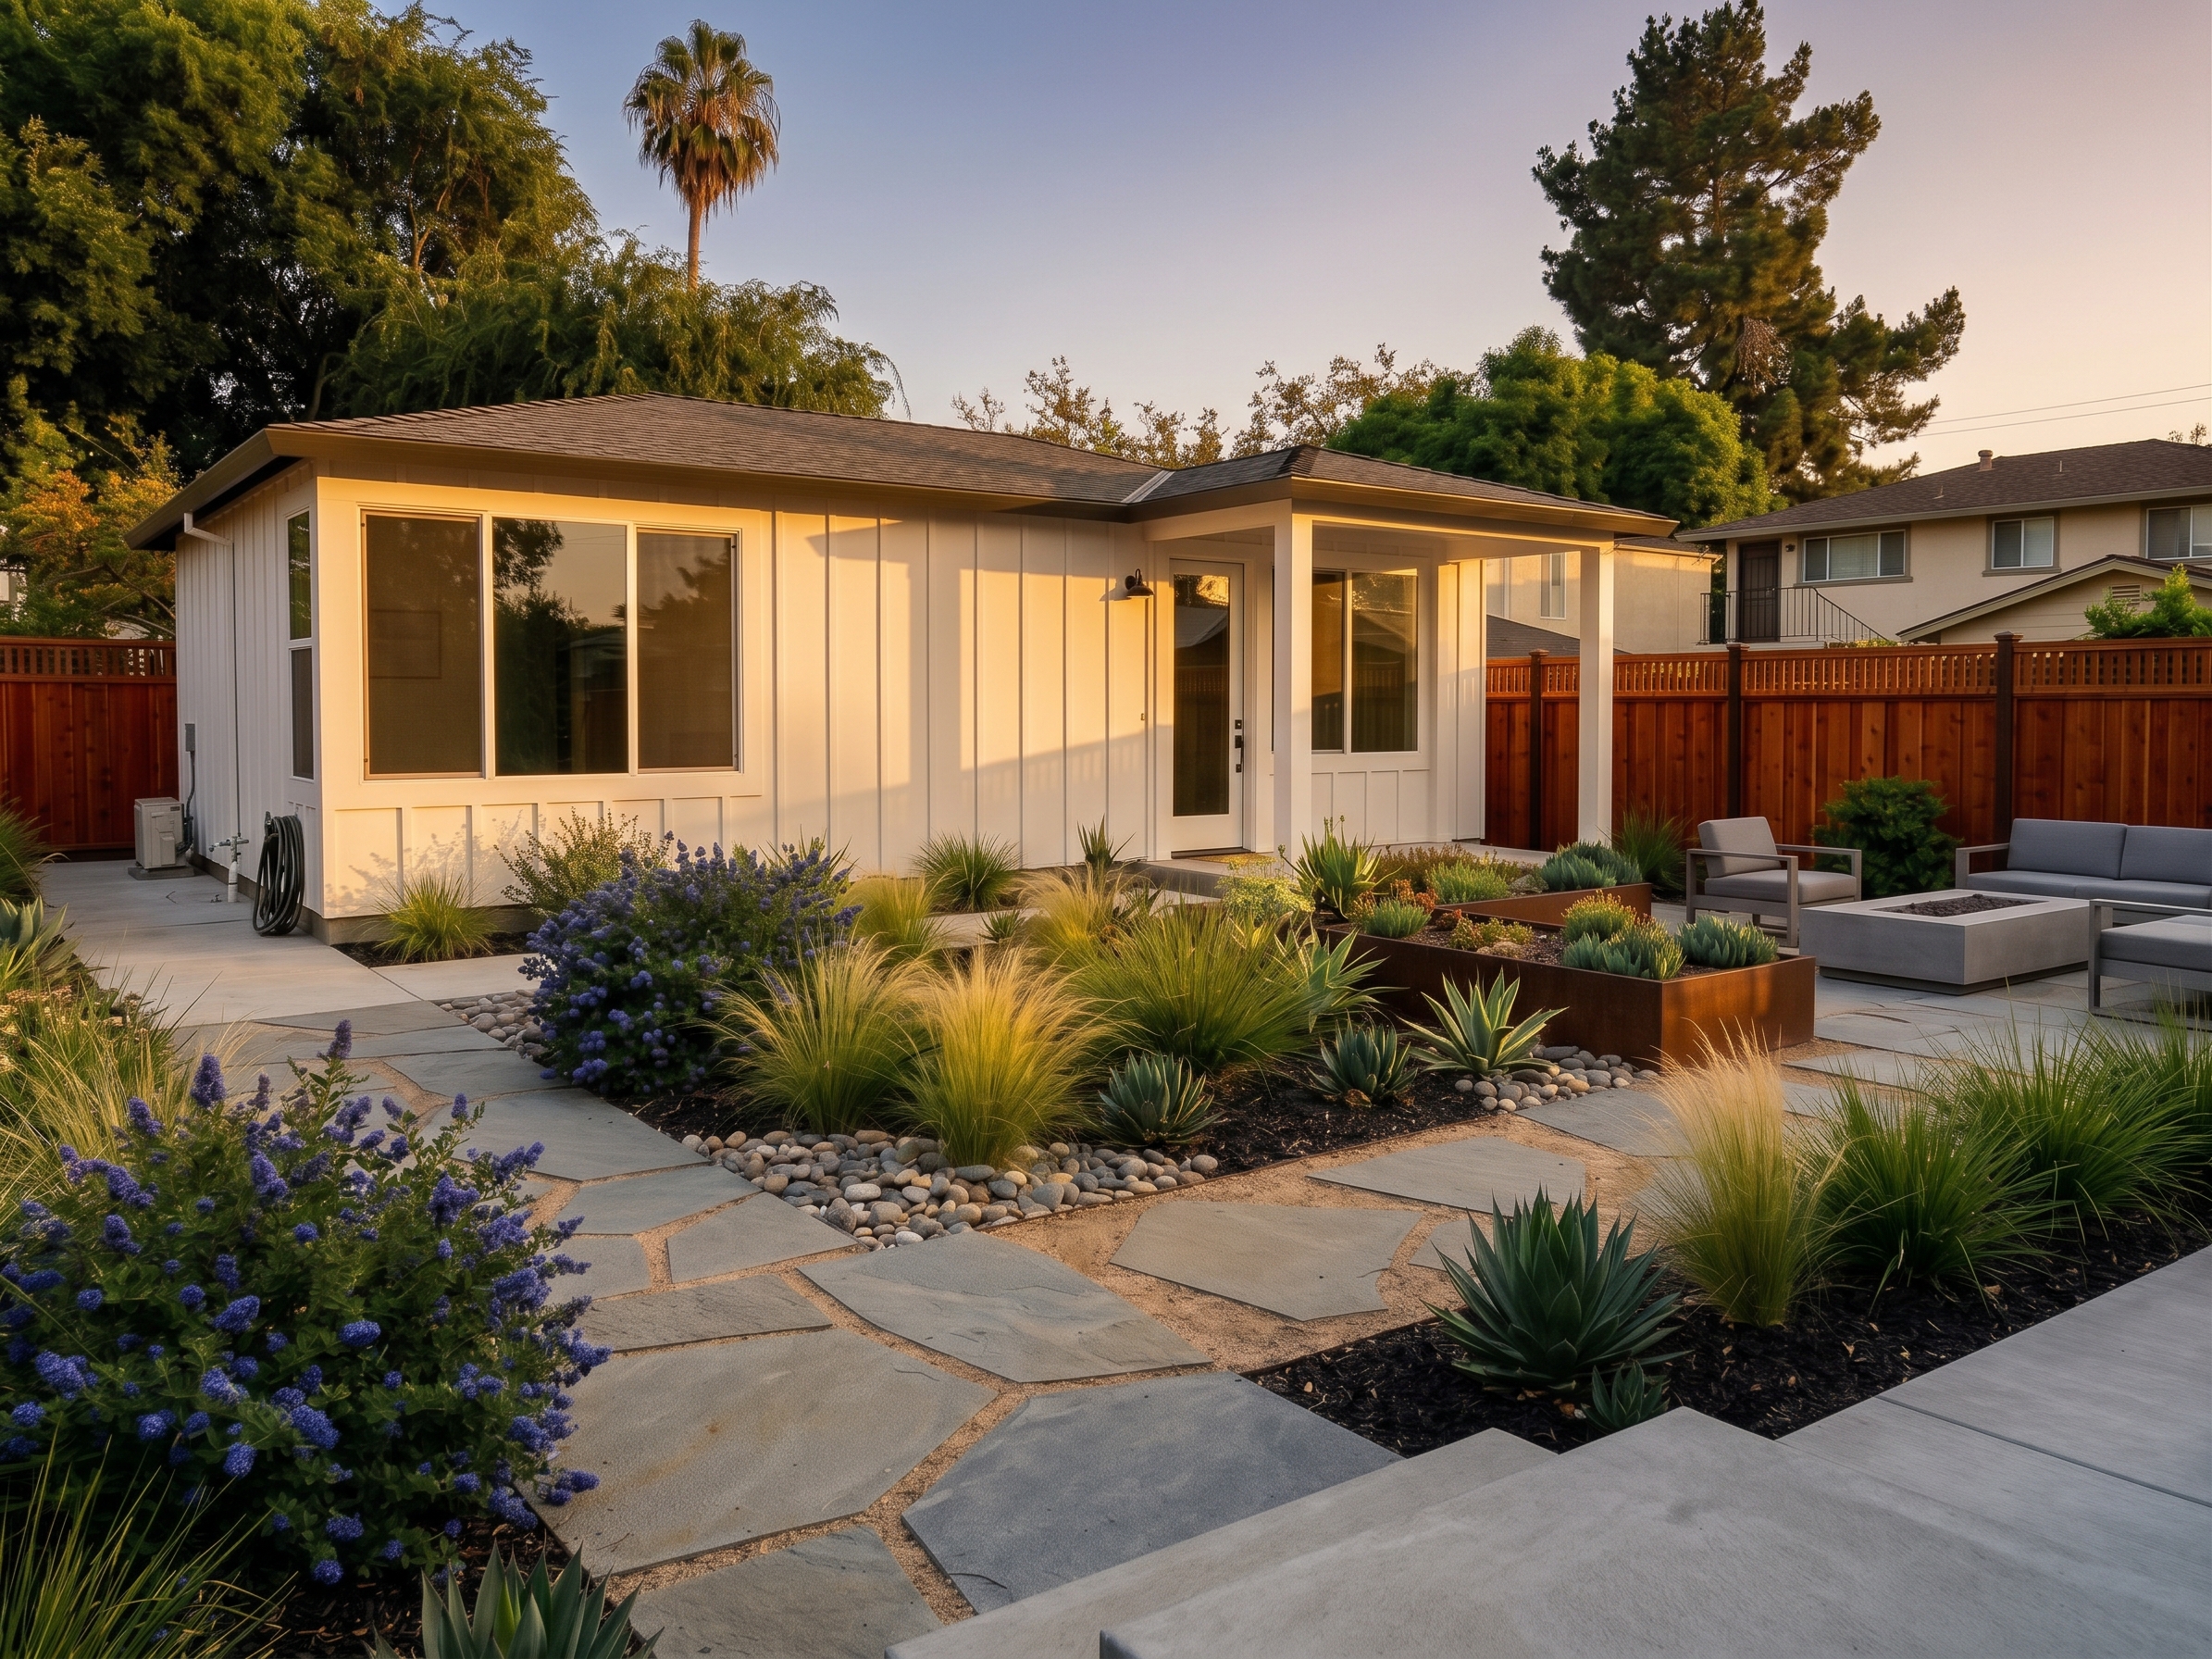
Completed Acton ADU, San Jose
A well-designed, traditionally built ADU is often appraised at a similar price per square foot as the main home. Appraisals on our completed projects consistently show homeowners adding more value than they invested.
Once the value is added, the ADU appreciates with the rest of the property. Ten or fifteen years out, that can mean hundreds of thousands of dollars in additional family wealth.
Rent helps carry the loan. So does the money a family does not spend on a care facility or a second rent check.
Equity and appreciation outcomes are illustrative and vary by property, design, city, and market. Talk with an appraiser or financial advisor about your own numbers.
An Acton ADU specialist asks what you want to build, roughly what it will cost, and how you are thinking about paying for it.
Based on your situation, we connect you with the lending partner whose programs and credit requirements fit. You talk to them directly; we stay in the loop.
The lender walks you through loan types, amounts, and estimated payments for your property. If the numbers do not work for you, there is no obligation to go further.
We work with multiple lending partners so you can be matched with the right fit for your situation: flexible credit requirements, fast approvals and closings, and streamlined qualification. You get the introduction; the lender handles the rest.
"Putting an ADU in your backyard is no small decision. I vetted 3 companies before making my final choice and frankly I could not be happier."
"For an ADU, the way to go is with Acton ADU as they design-build the project and work through all the permit hurdles."
Since 1990, with hundreds of Bay Area families and a 5.0 rating on Google. We understand your property before we price it, so the number you take to a lender is grounded in your site.
No. Most homeowners who build an ADU still have a mortgage. What matters is the equity you have built and the value the finished ADU adds, which is how home equity loans, HELOCs, and renovation loans are sized.
It depends on the lender and the program. We work with multiple lending partners with flexible credit requirements, so submit the form and we will match you with the one whose requirements fit your situation.
That is what the introduction is for. Tell us how you are thinking about paying for the project and we will connect you with the lending partner whose programs fit. They will walk you through the options for your property and finances.
It depends on the loan type and the lender. Our partners offer fast approvals and closings, and we time the introduction so funding lines up with your design and permit schedule.
Yes. Build Ready plans come with complete drawings, engineering, and a defined scope, which makes them straightforward for lenders to appraise and fund.
Nothing. Connecting you with a lending partner is part of helping you get the project built.

Thirty seconds to submit. One call from us. Then an introduction to the lending partner that fits. No obligation at any step.